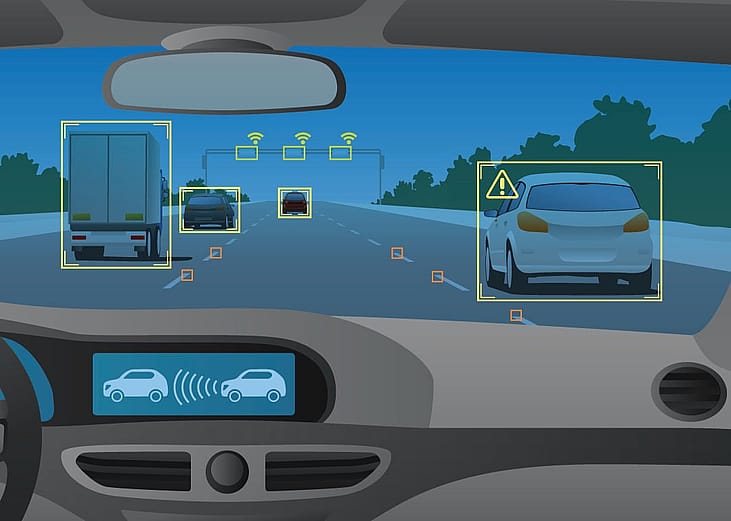
New vehicles often have thousands of fragile semiconductor chips to support advanced features like collision, lane-departure, and blind-spot warnings. Safety technologies can help drivers avoid crashes and accident-related premium hikes but are also expensive to repair.
Vehicle maintenance and repair costs have increased by nearly 38% over the past five years, according to the BLS CPI.
Advanced driver-assistance systems, or ADAS, can add up to 37.6% to the total repair cost after an accident, AAA data shows. Minor damages to front radar and distance sensors can add up to $1,540 to the bill.
EVs pose an additional challenge. They take an average of 5.8 days longer and cost 46.9% more to repair than gas-powered cars, with an average repair cost of $6,700, according to CCC data.
Mechanic labor hours have grown by 40% per claim over the last decade as technologies in newer models become increasingly complex. Finding an auto mechanic without a backlog to perform that labor can be difficult. The U.S. is facing a shortage of 495,000 auto technicians and 110,000 collision repairers, according to a TechForce Foundation study.
As new vehicle prices have risen and inflation has strained Americans' finances, drivers are holding onto their cars for longer. The average U.S. vehicle age reached a new record of 12.6 years in 2024, according to S&P Global Mobility.
Though most insurers offer new vehicle discounts because the cars are more reliable and safer in accidents, insurance is cheaper for older vehicles. Full coverage for a 2011–2012 model year Honda Civic averages $1,968 annually, but insuring a 2023–2024 model costs 74% more, at $3,425 annually.
The 2024 Honda Civic has multiple high-tech safety features, including lane-keeping assistance, traffic sign recognition, collision mitigation braking, and adaptive cruise control.
Auto Insurers Push Telematics for Relief From Premium Hikes
Drivers facing premium hikes may look to insurance discounts to lower their costs. Most insurers offer numerous ways to save, including bundling home and auto insurance, taking defensive driving courses, and achieving a certain number of years without an at-fault accident or other moving violation.
But insurance companies are increasingly interested in pricing risks based on policyholders' driving behaviors rather than factors like gender, place of residence, or credit-based insurance scores, says Stella. Telematics insurance programs give insurers that ability.
Telematics-based insurance tracks driver behavior through smartphone apps or plug-in devices. Insurers use this driving data to determine premiums, reducing the cost for cautious drivers who follow traffic laws and increasing it for behaviors like hard braking, speeding, and rapid acceleration.
Telematics insurance savings vary. Progressive's Snapshot telematics program saves drivers an average of $231 annually, and Nationwide's SmartRide offers up to 40% off premiums.
"It remains to be seen how much premiums will be reduced for the safest drivers, but there doesn't seem to be doubt [from insurers] that they will be," Stella said. "Insurers also see opportunities to use telematics data to make driving safer for everyone on the road. Alerting riskier drivers to their unsafe behaviors, for instance, may reduce instances of those behaviors—particularly if there are incentives to drive more safely."
Data shows the benefits of telematics for road safety and insurance rates. By participating in a telematics program, the least-safe drivers decreased distracted driving behaviors by an average of 20% and hard braking by 9%, reducing estimated bodily injury claims by 5.5%, according to a Cambridge Mobile Telematics study.
Catastrophic Losses and Expensive Repairs Continue to Strain Insurers and Drivers
Despite signs of market stabilization at the beginning of the year, premium increases have continued in 2024. By the end of the year, Insurify's data science team expects a 22% year-over-year increase in full-coverage rates, bringing the average annual cost to $2,469.
Rising vehicle repair costs and more complicated and expensive fixes for newer cars with ADAS are significant drivers of rising premiums.
Drivers in states with frequent heavy storms, hail, hurricanes, and wildfires—an increasingly large portion of the country—will likely see the effect of climate catastrophes reflected in their premiums. As reinsurance companies raise rates, auto insurers pass some of that cost to policyholders.
But good news may be on the horizon for some drivers.
"Insurers implemented higher rate increases to account for changes in the frequency and severity of auto losses. The COVID-19 pandemic and following inflation, especially in the price of vehicle maintenance and repairs, along with changes in driving behaviors, led to new loss trends that increased the difficulty of rate setting," said Stella.
"Some insurers have started making downward adjustments in areas where they've found opportunities to operate profitably while charging lower rates," she said. "Generally, consumers will continue to see rates rise with inflation, or in areas where traffic accidents are increasing, but in some states, they could see premiums decrease a little again."
In the meantime, drivers who saw their premiums rise can take steps to lower their insurance costs. Comparing rates with multiple insurance companies can help drivers save hundreds of dollars annually on comparable coverage.
Insurers also offer discounts for accident-free drivers, military members and their families, certain vehicle safety features, multi-vehicle policies, and more. Raising deductibles can bring premiums down, and telematics programs can further reduce costs for cautious drivers.
Methodology
Insurify's data scientists examined more than 97 million rates in its proprietary database, quoted via integrations with partnering insurance companies. Driver applications originate from all 50 states and Washington, D.C., and include information on the exact coverage specifications of each driver's quoted policies. Insurify excluded Alaska data due to lower quoting volume.
The premiums in this report reflect the median insurance cost for drivers between the ages of 20 and 70 with clean driving records and average or better credit, unless otherwise noted. Yearly prices in this report are two-year rolling medians to manage extreme market volatility over the past few years.
Liability-only premiums correspond to policies with bodily injury limits between state-minimum requirements and $50,000 per person, $100,000 per accident; property damage coverage between $10,000 and $50,000; and no additional coverage. Full-coverage premiums reflect the same bodily injury and property damage limits, plus comprehensive and collision coverage with deductibles of $1,000. To download more auto insurance data, visit Insurify's data center.