How many Americans have an 800 credit score in 2026?

About 54 million U.S. adults (roughly 1 in 5) have a FICO Score of 800 or higher, according to a Kikoff analysis of Experian’s June 2026 FICO Score data. That’s 22.9% of consumers with a credit score. Just 1.71%, or about 4 million adults, have a perfect 850 FICO Score.
A score that high can help you qualify for a lender’s lowest rates, and over the life of a loan, that difference can add up. Here's who's reaching 800, where they live, and the financial habits they rely on.
What percentage of Americans have an 800 credit score?
Experian, one of the three major credit bureaus, found that 22.9% of consumers with a credit score have a FICO Score of 800 or higher, based on its latest FICO Score 8 data from June 2026. FICO says its scoring models are used by 90% of top U.S. lenders, with FICO Score 8 among its most widely used.
Older adults are likelier than any other generation to have an 800+ FICO Score, but the bigger story is the group just below 800: people with a “very good” FICO Score (740 to 799), the largest share of any range. That’s an estimated 65 million adults, based on Kikoff’s analysis. If you’re one of them, 800 may be just a step, not a leap.

One heads-up: The score you see in a financial app may be a VantageScore, a different scoring model from the FICO Score many lenders use, which means it may not line up exactly with these ranges.
How rare is a perfect 850 FICO Score?
An 850 is about as rare as credit gets. Just 1.71% of scored consumers, fewer than 2 in 100, have a perfect 850 FICO Score, according to Experian’s June 2026 data. That’s about 4 million adults, based on Kikoff’s analysis.
People with an 850 have the same habits as the 800+ FICO Scores crowd, just taken a little further. According to Experian, they use about 4% of their available credit, versus 29% for all consumers. They average 5.6 credit cards, with zero accounts ever reported late.
FICO puts every score from 800 to 850 in the same top “exceptional” range, so an 850 may not open many doors an 800 doesn’t.
Is an 800 credit score more common than it used to be?
Yes, it’s slowly becoming more common. The share of consumers with a FICO Score of 800 or higher rose from 19.5% in 2016 to 22.9% in 2026, up 3.4 percentage points, according to Experian.
FICO’s numbers point the same way: A record 48.1% of consumers had a FICO Score of 750 or higher in the spring 2026 report. But the national average FICO Score went the other way. It dipped to 714, which FICO tied mainly to missed student loan payments showing up on credit reports again, and held there in FICO's fall 2026 report.
Taken together, the numbers suggest scores are spreading apart, so good credit habits might matter more than ever.
Who has an 800 credit score?
The answer is that it’s generally older adults. The length of your credit history is one of the factors scores weigh, and there’s no shortcut for time.

Put another way, fewer than 1 in 20 Gen Zers have a FICO Score of 800 or higher, according to Experian. Compare that with about 1 in 6 millennials, about 1 in 4 Gen Xers, and more than 1 in 3 baby boomers. Gen Z’s average FICO Score of 678 already falls in FICO’s good range (670 to 739). If that’s you, you’re not behind, just early.

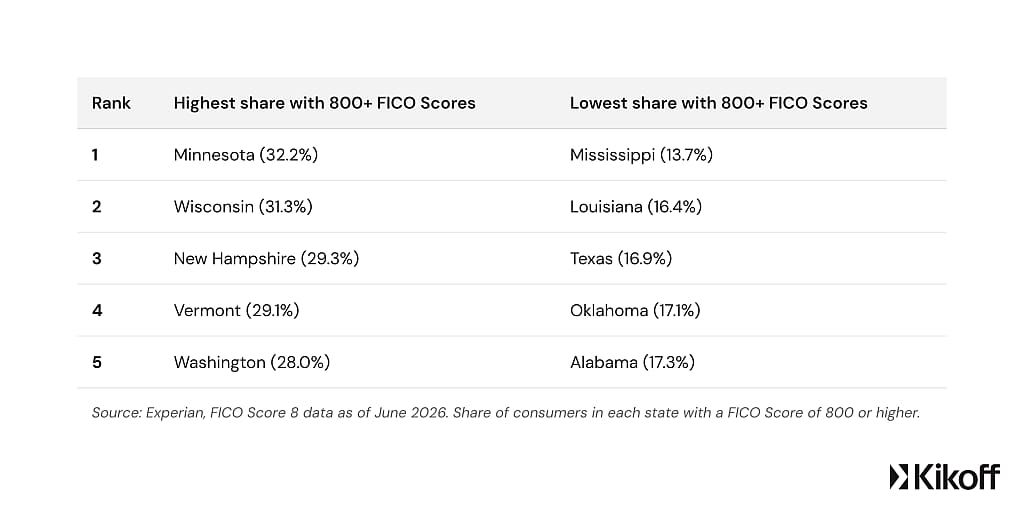
Which states have the highest share of 800+ FICO Scores?
Minnesota leads, with 32.2% of consumers at a FICO Score of 800 or higher, and Mississippi has the lowest share, at 13.7%, according to Experian.
What do people with 800+ FICO Scores do differently?
Two things, mainly. They use a small slice of their available credit, and they rarely, if ever, pay late.

People with FICO Scores of 800 or higher tend to have more credit cards than others, but they don’t lean on them much. Their balances take up about 7% of their limits, compared with 29% for all consumers. That share, called your credit utilization, is one of the bigger factors in your score.
They also rarely pay late, averaging 0.01 accounts ever reported late versus 1.63 for all consumers. Payment history carries more weight in your score than any other factor, so every on-time payment counts.
The good news is that both habits are in your control. Paying down balances before your statement closes is a good place to start.
If paying down balances feels out of reach, the National Foundation for Credit Counseling can connect you with free or low-cost debt counseling at 800-388-2227.
What does an 800 credit score get you?
In a nutshell: cheaper borrowing. The median personal loan APR (annual percentage rate, or the yearly cost of borrowing) offered was 13% for people with exceptional FICO Scores (800 to 850) versus 19% for people with good FICO Scores (670 to 739), according to Experian. On a $10,000 fixed-rate loan repaid over three years with no fees, that’s about $30 more a month, or roughly $1,070 more in interest over the life of the loan.
Still, you don’t need an 800 for solid credit offers from lenders. A FICO Score in the good range (670 and up) can open plenty of doors on its own.

Bottom line
About 1 in 5 U.S. adults has a FICO Score of 800 or higher, and people at that level tend to share two financial habits: low balances and on-time payments. Your credit affects more than whether you’re approved. It also shapes the rate you’re offered, so the history you build before you apply counts.
Methodology
Experian reports the share of consumers in each FICO Score range, but not how many people that represents. To estimate a head count, Kikoff started with the U.S. Census Bureau’s estimate of 269.8 million U.S. adults as of July 2025. The researchers narrowed that to the 87.5% of adults the Consumer Financial Protection Bureau estimates had a scored credit record in 2020, or about 236 million people. The CFPB’s own count for December 2020 was 225.3 million scored adults out of roughly 258 million. The researchers’ figure is higher because they applied the same 87.5% share to the larger 2025 adult population. They then applied Experian’s June 2026 percentages for each FICO Score range. That gives about 54 million adults with a FICO Score of 800 or higher (22.9% of scored consumers), or roughly 1 in 5 U.S. adults, and about 4 million with a perfect 850 (1.71%). Experian’s data uses FICO Score 8, which FICO says is the version most widely used by lenders. Headcount estimates are rounded to the nearest million. All figures were confirmed in November 2026.
These are estimates. The sources cover different years (2020 to 2026), and Experian’s data reflects its own credit files, so the numbers won’t line up perfectly with the full U.S. population. Other scoring models, including VantageScore, may place the same person in a different range. This analysis uses only public data from Experian, FICO, the Census Bureau, and the CFPB. It doesn’t use any Kikoff customer data.
This story was produced by Kikoff and reviewed and distributed by Stacker.