Ramp
1 / 1Can You Build Personal and Business Credit at the Same Time?
Personal credit cards don't build business credit, and vice versa, so you cannot build personal and business credit at the same time. Use business credit cards and personal credit cards separately, limiting business credit cards to business expenses.
Whose Credit Do Business Credit Cards Affect?
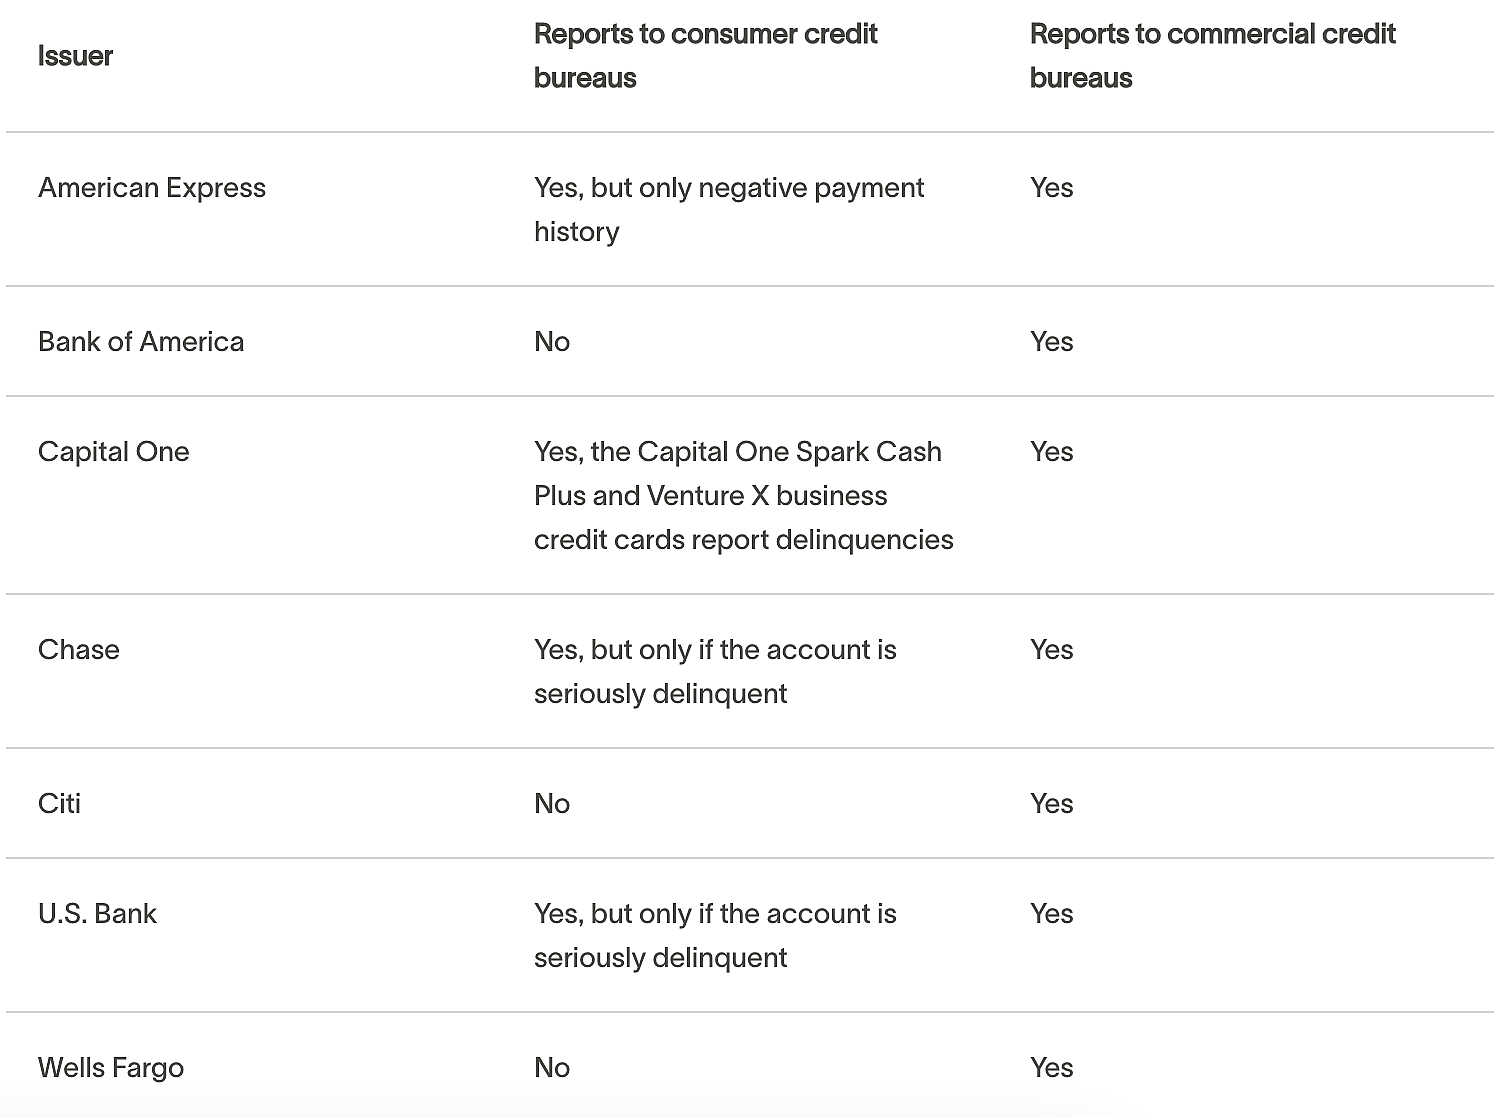
When business credit card activity is reported to the consumer credit bureaus, it typically only affects the primary cardholder—that is, the business owner who opened the card and personally guaranteed any credit card debt. Sometimes, a business owner may add an authorized user to their business credit card. In that case, the authorized user's credit report could also be affected.
Here's what it means to be a primary cardholder or an authorized user on a business credit card:
Primary cardholders
Whoever applies for and is approved for a small business credit card is considered the primary account holder. Usually, this is the owner of the company, not an employee.
When you open the card as the primary account holder, the tax identification number you provide will determine whether the card reflects on your personal or business credit score. If you open the card with your SSN, it'll be linked to your personal credit score. Opening the card with your business's EIN will keep your business credit score separate.
If you open a card with your SSN, you'll probably also have to provide a personal guarantee of repayment so that lenders know you'll personally repay any debts if your business account defaults on its payments.
Authorized users
An authorized user is someone who has been added to a credit card account by the primary cardholder—usually, this is an employee. This allows the employee to make purchases on the card as if it were their own.
As an authorized user, your credit score will reflect how both you and the primary cardholder use the card. If the account holder makes timely payments, then it'll help build your credit score. If the account holder fails to make payments, however, your credit score will take a hit.
If a card can be used by more than one person, the business needs a system that identifies who used the card and who must approve the purchase.
Does a Corporate Credit Card Affect Your Credit Score?
Generally, with corporate credit cards, your personal credit score won't be affected. This is because most corporate cards are opened using your business's EIN number, not your personal SSN. Business owners and employees both shouldn't see any changes to their personal credit scores when a corporate card is used.
As a business owner, corporate cards differ from traditional business credit cards in how they affect your business credit report. This is because:
- Corporate cards don't factor in credit utilization ratios. That means you don't have to worry about how much of your available credit you've used out of your credit limit, like you would with a traditional credit card.
- Corporate cards typically require full monthly balance payments, often automatically drawing from your business bank account. This eliminates the possibility of late payments and credit card debt being reported to the credit bureaus.
The only case in which a corporate card would affect an employee's personal score is if the business made a billing mistake and added it in their name. If you see that a corporate charge card appears in a personal credit check, take steps to speak with the person in your company issuing the cards to remove your name.
How Does an LLC Affect a Credit Report?
If your LLC has debts taken out in the company's name, only the LLC's credit score will be impacted by whether you repay your debts on time. An LLC loan will only impact your personal credit if you cosign or guarantee it. If you don't do so, your personal credit report will remain unaffected.