Wealth Enhancement Group
1 / 4In your 40s
Max out your retirement accounts
You need to save a lot of money for retirement—especially in your peak earning years. This is a time when you're likely benefitting from an employer-sponsored health plan, and you may even be enjoying a hard-earned break from the expenses of raising and educating children. Take advantage of it by contributing as much as possible to your retirement accounts.
Make Roth IRA contributions
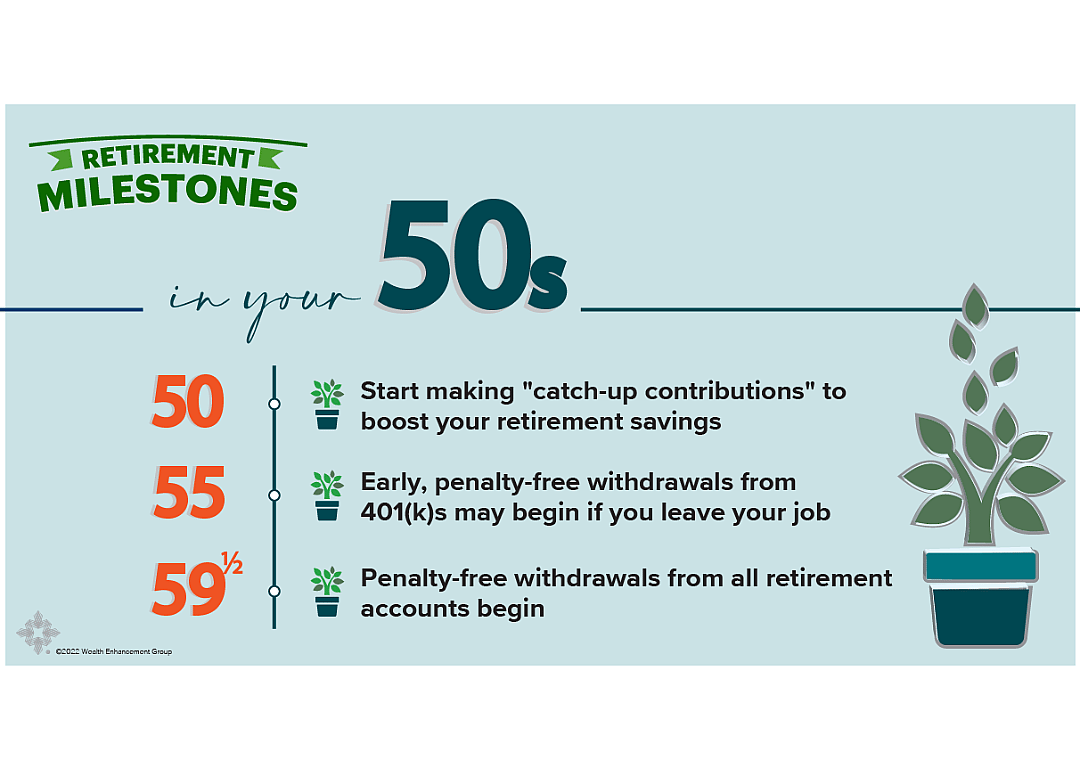
There are limits to how much you can contribute to your Roth IRA. In 2023, if you're under age 50, you can only contribute up to $6,500 for the entire year. If you're over 50, you can contribute an extra $1,000 in catch-up contributions.
Even then, the amount you can contribute is dependent on your income. Once you reach a certain limit, the amount you can contribute starts to phase out. Contributing to your Roth IRA early allows for longer tax-free growth and ensures you don't lose the opportunity to make contributions.
Start building tax diversification
Tax diversification is intentionally distributing your assets between various investment accounts that are taxed differently. Just like you should have diversification in your investments, you should also have diversification in how your retirement accounts are taxed.
Essentially, this means you should start spreading your assets around various accounts that are taxable, tax-deferred, or tax-advantaged. This strategy allows a more even distribution of your tax burden throughout your life by allowing you to vary what sources you draw income from based on your circumstances.