TeacherCertification.com
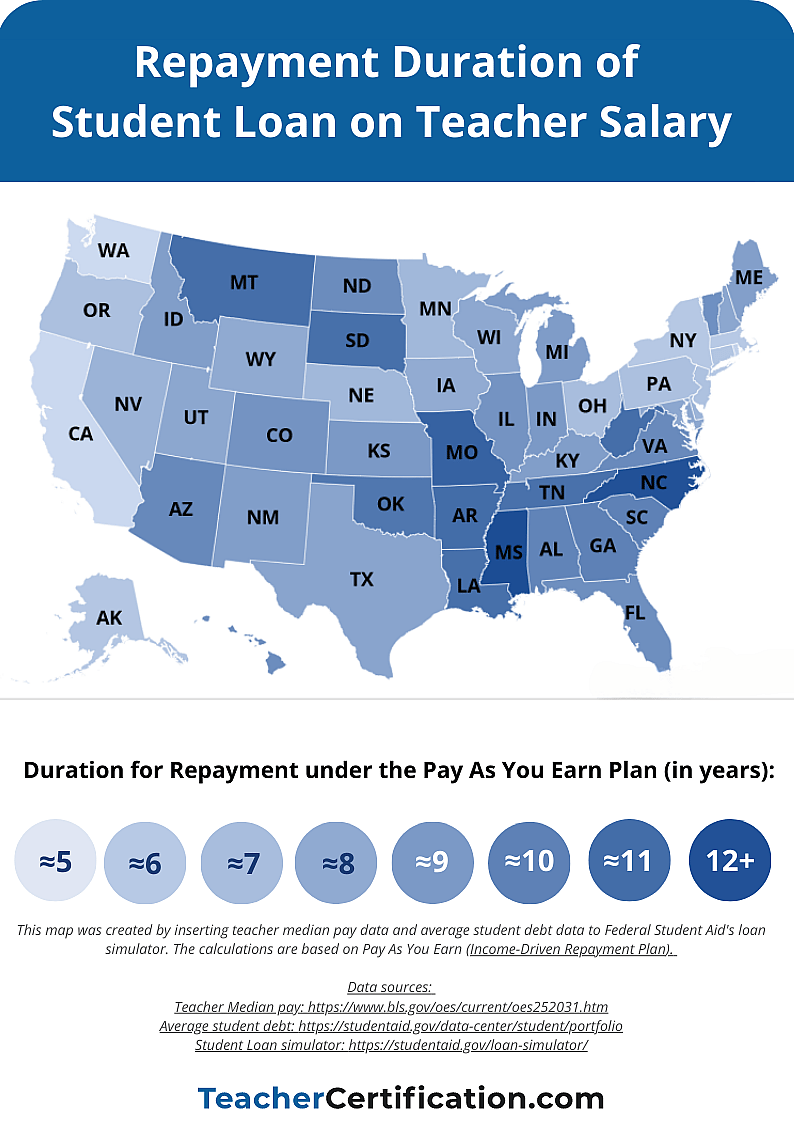
1 / 3State trends show that repayment duration varies widely
National data suggest that it takes an average of 8.7 years for teachers to repay their debts. However, this can depend on where you teach.
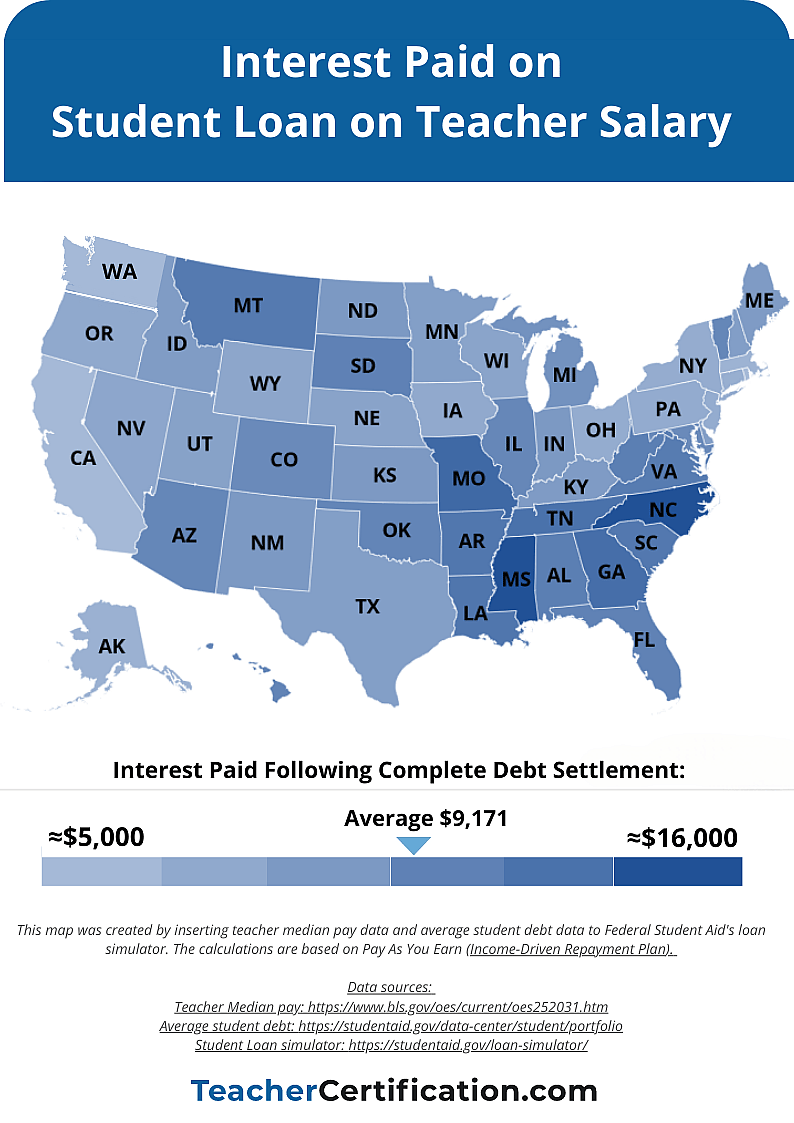
To find out where it takes the longest for teachers to repay their loans, we dove into the numbers armed with the Federal Student Aid's Loan Simulator. Our mission was to shed light on the interest paid, repayment times, and estimated monthly payments by the average student loan borrower, factoring in the unique circumstances of educators in each state.
We focused on the Pay As You Earn (PAYE) repayment plan, which offers more manageable monthly installments. For the calculations, we used the median salaries for secondary school teachers.
Over half of the teachers incurred a student loan debt of $58,700 in 2020, which exceeds the state averages. It is important to note that not all teachers take out student loans to fund their education. Since there is a lack of state-specific data concerning teacher debt, we've utilized the state average student debt amount for our calculations. We also assumed that teachers' salaries would increase by 5% annually, which is a generous assumption.
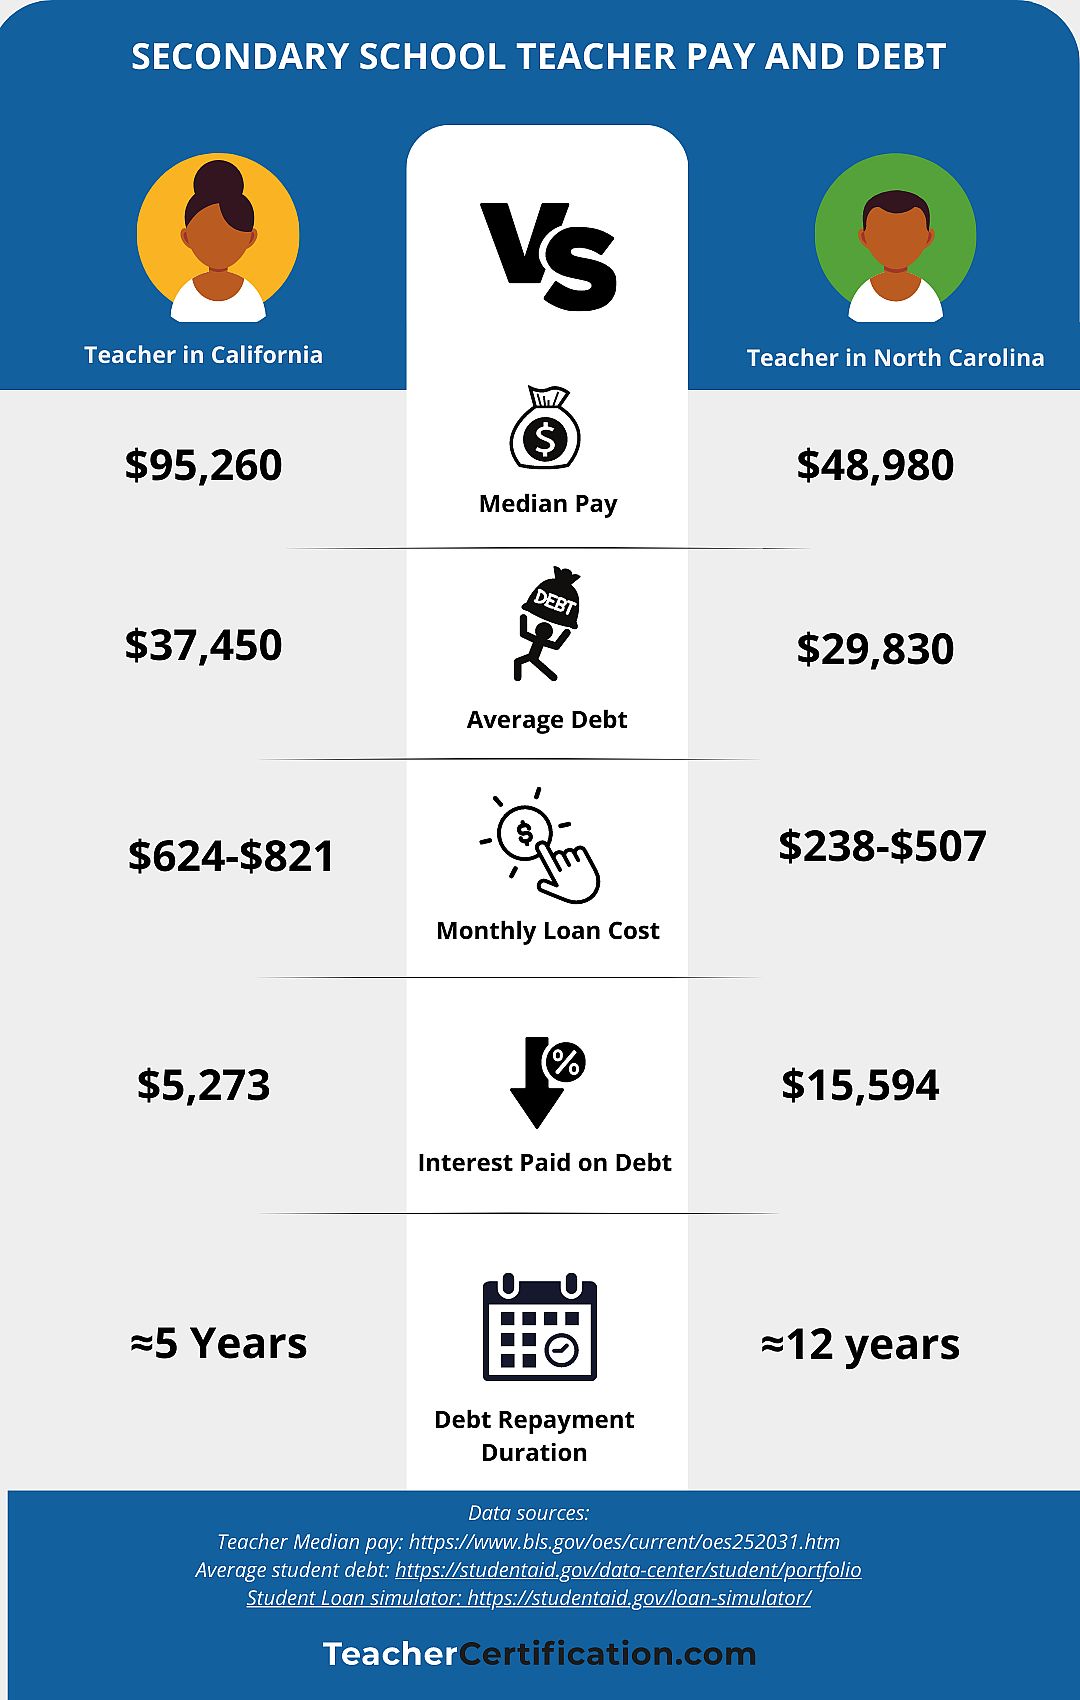
The data demonstrates that the states where it takes teachers less time to repay their loans are also the states where teachers are paid the most: California, Rhode Island, Massachusetts, and New York. In all these states, secondary school teachers earn, on average, more than $79,000 a year. With higher salaries, teachers can pay back their loans in 5 to 6 years on a Pay As You Earn Plan.
In states with the lowest teacher pay, which include Mississippi, South Dakota, West Virginia, and North Carolina—where secondary school teacher pay is below $49,000 a year—it takes more than 11 years to pay back the loans.